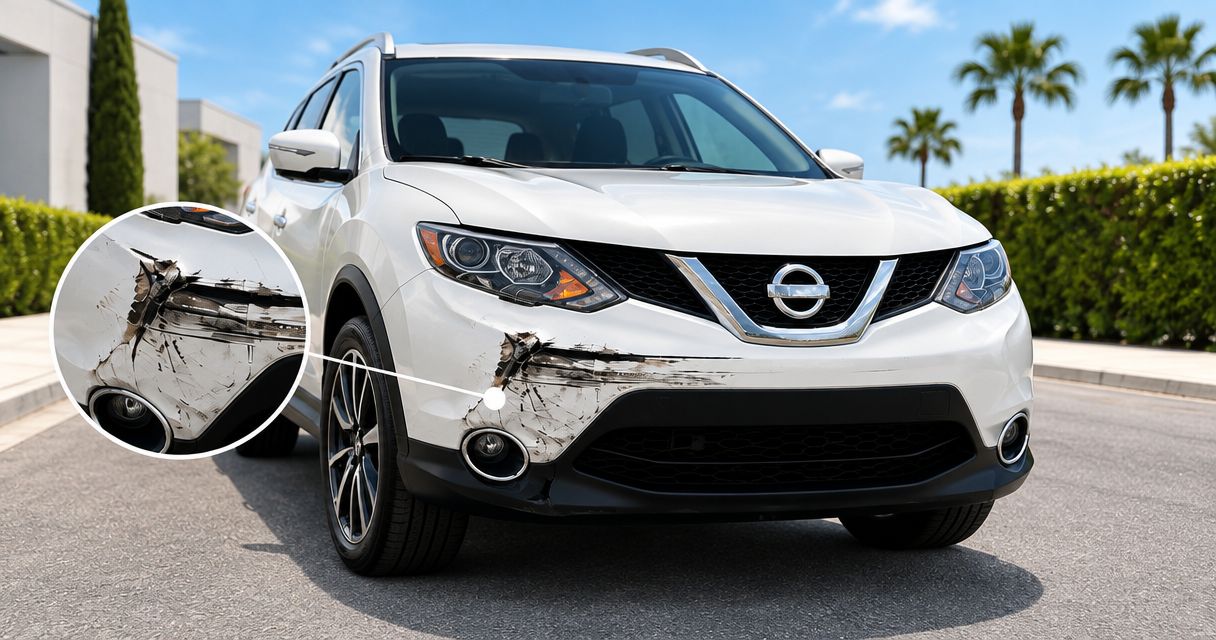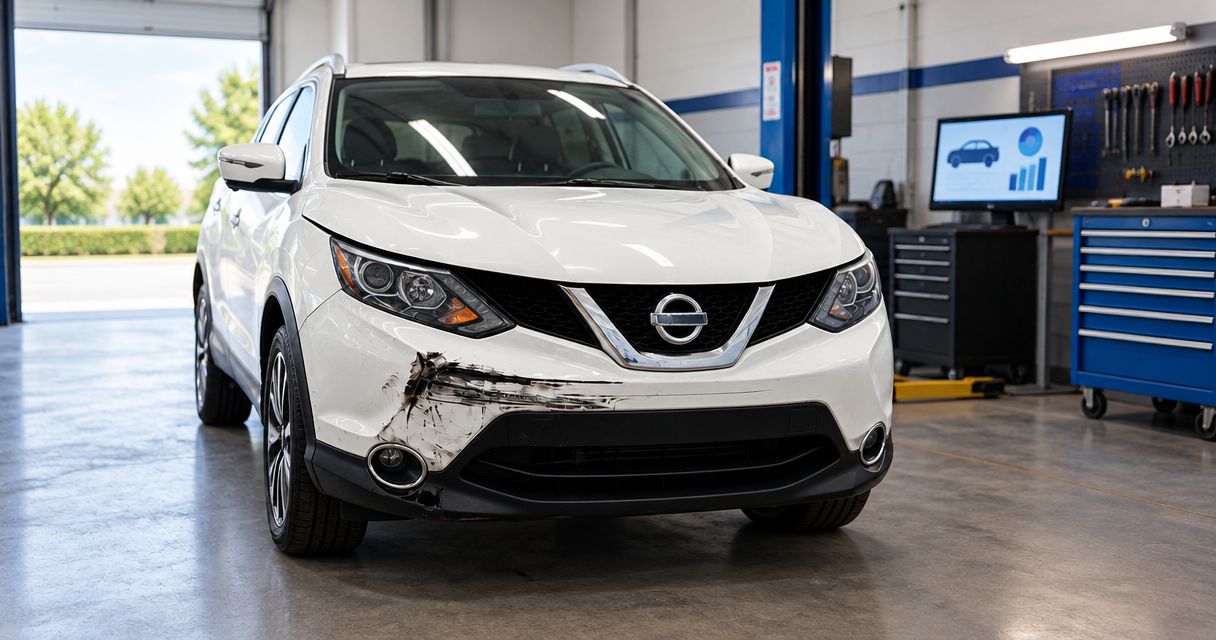
A bumper repair is worth an insurance claim when covered damage exceeds your deductible enough to make the claim useful; self-pay deserves a look when you would cover most of the repair yourself. Before deciding, get a written estimate, check your coverage, and separate visible bumper damage from anything damaged behind it.
- Compare bumper repair cost with your deductible before choosing insurance or self-pay.
- A bumper scratch alone does not reveal the full collision repair scope.
- Best Collision Center Long Beach handles collision repair and insurance claims for Long Beach drivers.
- Deductible assistance and free rental car coordination depend on eligibility; request a review before relying on either.
Is a bumper repair worth an insurance claim?
Choose based on the inspected damage and your policy—not the size of the mark on your bumper. A claim that pays little toward the repair offers a different benefit from one covering substantial damage. A repair estimate tells you what needs fixing; your policy and claim review establish what insurance covers.
For help with both parts, Best Collision Center Long Beach handles auto collision repair and insurance claim handling. Smaller cosmetic repairs and self-pay enquiries are welcome, too.
| Payment route | Best for | Main benefit | Main limitation |
|---|---|---|---|
| Self-pay | Drivers handling a repair without insurance reimbursement | You approve the repair scope directly | You pay for the work and any additional damage you authorize |
| Your own insurance claim | Drivers with applicable coverage and damage that makes the deductible worthwhile | Insurance contributes toward covered repairs under the policy | Your deductible and coverage terms still apply |
| Another driver's liability claim | Drivers seeking payment from an insurer that accepts its policyholder's liability | Payment follows the accepted liability claim | Liability and repair scope need review before payment is settled |
None of these routes wins automatically. If another vehicle, an injury, or a liability dispute is involved, the decision reaches beyond your bumper repair bill.
Why this matters for Long Beach drivers
After an accident, you want your car fixed without another surprise. The mistake is treating a bumper repair quote, an insurance estimate, and a final repair bill as interchangeable. They serve different purposes.
For a 2026 repair decision, start with a written scope rather than a general internet average. The useful question is not simply whether a bumper repair is expensive. It is what you would owe under each payment route for the same necessary repair.
Keep the repair decision separate from any accident-reporting obligations. Choosing self-pay does not erase policy conditions or responsibilities involving other people. Check those requirements before deciding not to involve an insurer.
How to compare bumper repair cost with your deductible
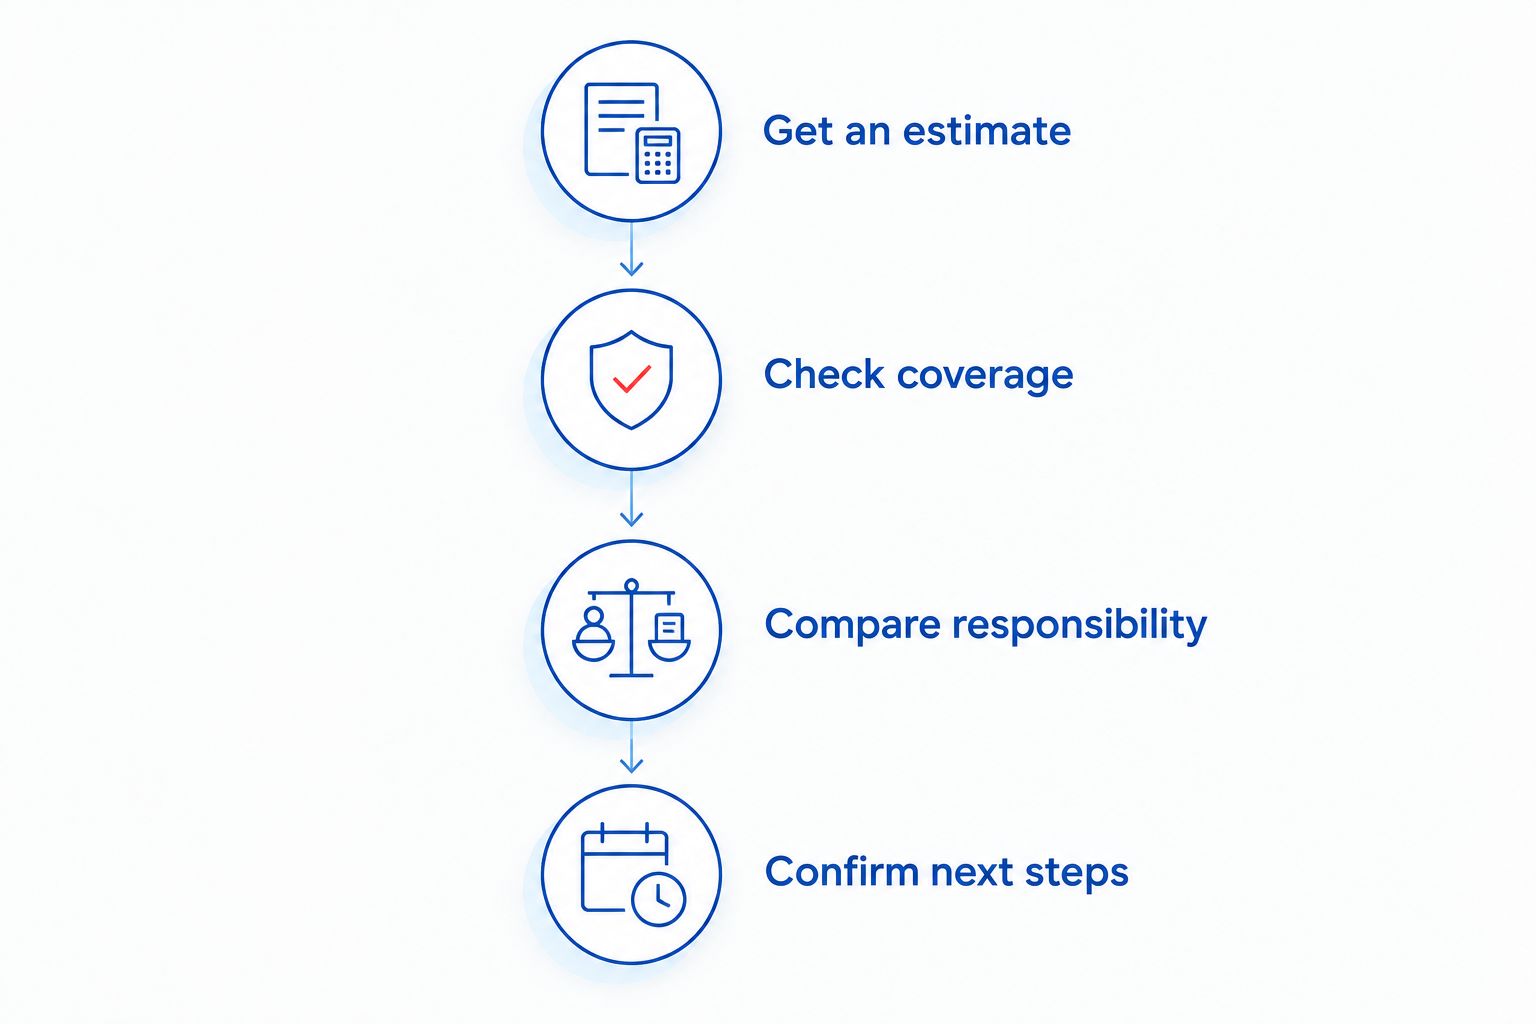
Use the following sequence before authorizing work. You do not need to know body-shop terminology to ask these questions.
- Get an estimate. Ask what damage the estimate includes, whether it is based on an exterior inspection, and what still needs checking. Request a written description of the proposed work.
- Check coverage. Confirm which coverage applies to the accident and which deductible applies to that coverage. Do not assume every type of bumper damage uses the same part of your policy.
- Compare responsibility. Ask what portion you would pay and what portion the insurer would pay if the listed repair is covered. Keep unapproved work separate from that comparison.
- Confirm next steps. Ask how additional damage will be documented, who approves additional work, and when you will hear about a change in your expected responsibility.
An estimate below your applicable deductible leaves no repair reimbursement under that deductible calculation. An estimate above it creates a potential insurance contribution, but the claim still needs applicable coverage and an approved repair scope.
Do not subtract the deductible from an unreviewed quote and treat the result as guaranteed payment. Coverage exclusions, unrelated damage, and disputed repair items affect the result.
When self-pay is the better fit
Self-pay is a practical option when the inspected repair is manageable for you and insurance would contribute little or nothing. It also lets you discuss a smaller cosmetic repair without assuming that every body-shop visit requires a claim.
The benefit is direct control over authorization. The trade-off is that you take responsibility for the repair bill, including additional work you approve after further inspection.
Ask the shop to distinguish necessary repairs from appearance-related work. A scuff and damaged attachment points are not the same concern. You can discuss cosmetic priorities, but do not leave safety-related damage unresolved just to reduce the scope.
Before accepting a self-pay estimate in 2026, confirm:
- Which damaged areas the estimate covers.
- Whether bumper removal or further inspection is needed.
- How the shop will contact you about additional findings.
- What work requires your authorization before proceeding.
Self-pay is not a reason to accept an unclear estimate. You still need a written scope and a clear approval process.
When your own insurance claim is the better fit
Your own insurance claim makes sense when the policy covers the event and the insurer's contribution meaningfully reduces your repair responsibility. It also provides a route for documenting additional accident-related damage found during the repair process.
The benefit is help paying for covered work. The limitation is that opening a claim does not approve every repair item or remove your deductible.
Ask your insurer which coverage applies before assuming the damage is covered. Contact with another vehicle, a fixed object, or an unidentified vehicle can raise different coverage questions. Describe what happened accurately instead of choosing a label yourself.
If the insurer's estimate differs from the shop's estimate, ask which specific repair items differ. A disagreement about removing a component, replacing a damaged part, or checking a system needs an item-by-item explanation—not a general argument about the total.
When another driver's insurer is involved
Another driver's liability insurer is a separate payment route. It depends on the insurer's review of responsibility and the accident-related damage, rather than simply on your decision to repair the bumper.
The benefit is pursuing repair payment through the party responsible for the accident. The limitation is that a submitted claim is not the same as accepted liability or agreed payment.
Keep photographs, driver information, correspondence, and the repair estimate together. Ask whether liability has been accepted and whether the insurer has reviewed the proposed repairs. Those are separate questions.
If you need repairs while liability remains disputed, ask your own insurer how your available coverage works in that situation. Do not authorize work based solely on an expectation that another insurer will reimburse it later.
Why bumper repair cost varies
Bumper repair cost depends on the work needed, not just the visible size of the damage. These factors explain why a quick visual guess and an inspected estimate differ:
- Repair or replacement: A damaged bumper cover needs assessment before deciding whether repair or replacement is appropriate.
- Paint work: Refinishing requirements depend on the damaged area, finish, and repair procedure.
- Damage behind the cover: Mounts, absorbers, reinforcement components, and surrounding parts need inspection when the impact warrants it.
- Vehicle equipment: On vehicles equipped with bumper-area sensors or related systems, the repair procedure needs to account for that equipment.
- Removal and inspection: Accessing hidden damage adds work that an exterior-only estimate does not establish.
- Additional findings: Damage identified during disassembly changes the scope when it was not visible during the initial inspection.
For a 2026 estimate, ask the shop to identify which of these factors actually applies to your vehicle. A list of possible repairs is not evidence that your car needs all of them.
Does a small bumper scratch mean the repair is minor?
A small bumper scratch does not establish that the entire repair is minor. The impact location, attachment condition, and components behind the cover still matter.
Photograph the visible damage, but let the inspection determine the scope. Point out any new warning messages, loose trim, unusual gaps, or changes you noticed after the accident. These observations help direct the inspection; they do not establish a diagnosis by themselves.
Avoid pressing a loose bumper cover back into place and assuming the problem is solved. Ask the shop to assess the attachment damage and explain what needs repair.
Will a bumper claim increase my insurance premium?
A bumper claim does not provide enough information to predict a premium change. Fault, claim circumstances, insurer rating rules, and applicable California requirements matter.
Ask your insurer about your specific situation rather than relying on a universal promise. No shop should guarantee that a claim will have no insurance consequences.
For your 2026 decision, separate what is confirmed from what remains unsettled. The repair estimate is one document; a prediction about a future renewal is not a substitute for insurer guidance.
Can deductible assistance make a claim worthwhile?
Deductible assistance changes your out-of-pocket comparison only when you qualify and understand the arrangement. Do not treat assistance as automatic or assume it changes the insurer's coverage decision.
Ask what eligibility requires and what responsibility remains yours. Confirm the arrangement before relying on it to authorize repairs.
Best Collision Center Long Beach is best for Long Beach drivers seeking collision repair with insurance claim handling. Deductible assistance and free rental car coordination are subject to eligibility; call for a review rather than assuming either applies to your accident.
A rental arrangement also needs its own confirmation. Ask how rental coverage or assistance works, what you must arrange, and what obligations remain yours. Do not assume repair coverage automatically includes rental transportation.
What to bring to a repair and claim review
Bring enough information to connect the damage, the estimate, and the insurance discussion. You do not need a perfect file before asking for help, but organized details reduce confusion.
- Your vehicle information and photographs of the damage.
- A plain description of how the accident happened.
- Your insurer's name and claim information, if a claim is open.
- Any insurer estimate or written coverage correspondence.
- Your applicable deductible information.
- Questions about transportation, self-pay work, or deductible assistance.
Ask the shop to explain the proposed repair in everyday language. You should understand what is being repaired, what is still awaiting inspection, and what needs insurer review.
The useful outcome is not pressure to file a claim. It is a clear repair scope and a clear explanation of your next decision.
Request a repair and claim review
Discuss your bumper damage, payment options, and eligibility for assistance before authorizing repairs.
FAQ
Is bumper repair cost usually worth claiming on insurance?
Bumper repair cost is worth comparing with insurance when applicable coverage would pay a useful share of the inspected repair. Check the deductible and approved scope before deciding; a claim is not automatically the better payment route.
Should I get a bumper repair estimate before filing a claim?
A written bumper repair estimate helps you compare payment options before choosing how to fund repairs. Still check your policy's accident-reporting requirements instead of assuming an estimate lets you postpone required notice.
Can I pay for a small bumper repair myself?
You can request a self-pay estimate for a small bumper repair. Ask what the estimate includes and how additional damage will be handled before authorizing work.
Does insurance cover damage behind the bumper?
Insurance coverage for damage behind the bumper depends on the policy and whether the damage belongs to a covered event. The shop should document additional findings for insurer review rather than assume payment is approved.
Will Best Collision Center Long Beach waive my deductible?
Best Collision Center Long Beach offers deductible assistance subject to eligibility, not an automatic deductible waiver. Call for a review and confirm your remaining responsibility before relying on assistance.
Can I get a free rental car during bumper repair?
Free rental car coordination depends on eligibility. Confirm the arrangement and any responsibilities before assuming rental transportation is included with your repair.
What should I ask before approving bumper repair in 2026?
Before approving bumper repair in 2026, ask for the written repair scope, your payment responsibility, and the process for additional findings. Also confirm who must approve changes before more work proceeds.
One last thing
Ask this before you authorize the repair: What happens if you find more damage? That question exposes the difference between an estimate you understand and a bill you were not prepared for.
Get a clear answer about documentation, insurer review, and your authorization. Even a modest-looking bumper repair deserves that conversation.
Related guides
- How much does bumper repair cost in Long Beach?
- Does insurance cover bumper repair after a parking lot accident?
- Is it cheaper to repair or replace a cracked bumper?
- How to compare auto body shops in Long Beach
If you are unsure which payment route fits, request an estimate or insurance claim review from Best Collision Center Long Beach. Insurance and self-pay repair enquiries are welcome. Call to discuss your damage and eligibility for deductible assistance or free rental car coordination—without assuming you need to file a claim first.